ESG Compliance Can Unlock Investment if Properly Implemented — NECA
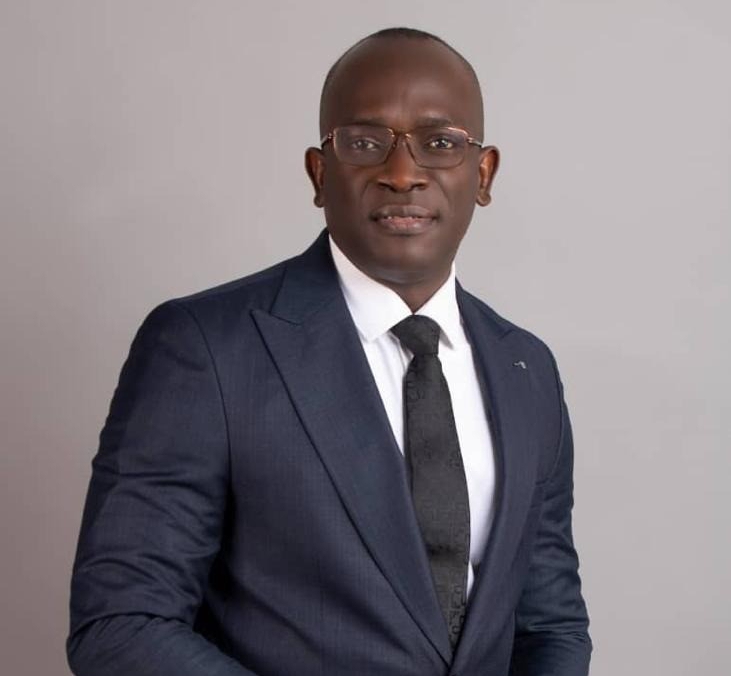
The Federal Government should implement Environmental, Social and Governance (ESG) requirements in a way that attracts investment without putting businesses at risk, the Nigeria Employers’ Consultative Association (NECA) has said.
NECA Director-General Adewale Oyerinde made the call in his keynote address at the 2026 Annual Workshop and Awards of the Commerce and Industry Correspondents Association of Nigeria in Lagos.
The workshop’s theme was “Fate of Nigerian Manufacturers in the New Tax Regime and Implications of Mandatory ESG on Nigeria’s Business Climate Ahead of the 2030 Deadline.”
Oyerinde said the Financial Reporting Council of Nigeria unveiled its amended roadmap and Sustainability Reporting Guideline 1 in February 2026 to support the adoption of IFRS S1 and IFRS S2.
Under the requirements, public interest entities, including listed companies, will report in line with the standards for periods beginning on or after January 1, 2028. Small and medium-sized enterprises will be covered from January 1, 2030.
While acknowledging the potential benefits of ESG reporting, Oyerinde cautioned that poor implementation could deter investment, add to business pressures and lead to job losses.
“NECA’s position is clear. ESG compliance must promote responsible business while remaining affordable and proportionate to the capacity of each firm. Poorly implemented, it becomes another cost that discourages investment, pushes MSMEs deeper into informality and costs Nigeria jobs.”
He pointed to the high cost of doing business, noting that unreliable electricity supply costs the Nigerian economy between N7tn and N10tn annually, while the Monetary Policy Rate remains at 23 per cent.
To support compliance, he called for flexible implementation, including simplified, tiered reporting templates for SMEs; a single reporting format and platform for regulators; practical training; and concessional financing for energy efficiency and cleaner production.
Oyerinde also said ESG pressures were growing in international markets, where exporters face increasing sustainability and carbon-related requirements.
He noted that the European Union’s Carbon Border Adjustment Mechanism, which came into effect on January 1, 2026, requires importers of products such as cement, iron and steel, aluminium, fertilisers, hydrogen and electricity to pay for embedded carbon.
“Since 1 January 2026, the European Union’s Carbon Border Adjustment Mechanism has made importers of cement, iron and steel, aluminium, fertilisers, hydrogen and electricity pay for the carbon embedded in those goods.”
The European Commission has proposed extending the mechanism to about 180 steel- and aluminium-intensive products from 2028, he added. Nigerian exporters unable to provide verified emissions data could face higher default values, making carbon reporting increasingly important to pricing and market access.
“For Nigerian exporters, carbon data now affects both price and market access,” he said.
Oyerinde said ESG standards were becoming central to business decisions, requiring companies to show how sustainability and climate-related risks could affect their financial performance.
“A manufacturer must show how energy costs and climate risk affect its earnings. A bank must assess the climate exposure of its loan book. An exporter must meet the carbon and labour requirements of its foreign customers. These are core business decisions.”
He argued that ESG compliance should not be treated solely as an additional regulatory burden, saying effective implementation could unlock investment, improve market access and create jobs.
“Capital follows credible disclosure. Nigeria’s Energy Transition Plan estimates that the country needs about US$410bn above business-as-usual spending by 2060, roughly US$10bn every year. Companies with reliable ESG data will be first in line for that capital.”
Businesses able to document their emissions, labour practices and governance would be better positioned to compete in Europe, global supply chains and the African Continental Free Trade Area, he said.
He also identified opportunities in renewable energy, recycling, waste management, energy efficiency and cleaner production.
“The Energy Transition Plan projects up to 340,000 new jobs by 2030 and 840,000 by 2060 if it is delivered,” Oyerinde said.
He urged the government to adopt a proportionate, business-friendly framework that helps Nigerian companies—particularly MSMEs—meet ESG requirements without undermining their survival or competitiveness.